The Fed Just Raised Rates for the First Time Since 2023: What San Diego Home Buyers, Sellers, and Investors Need to Know
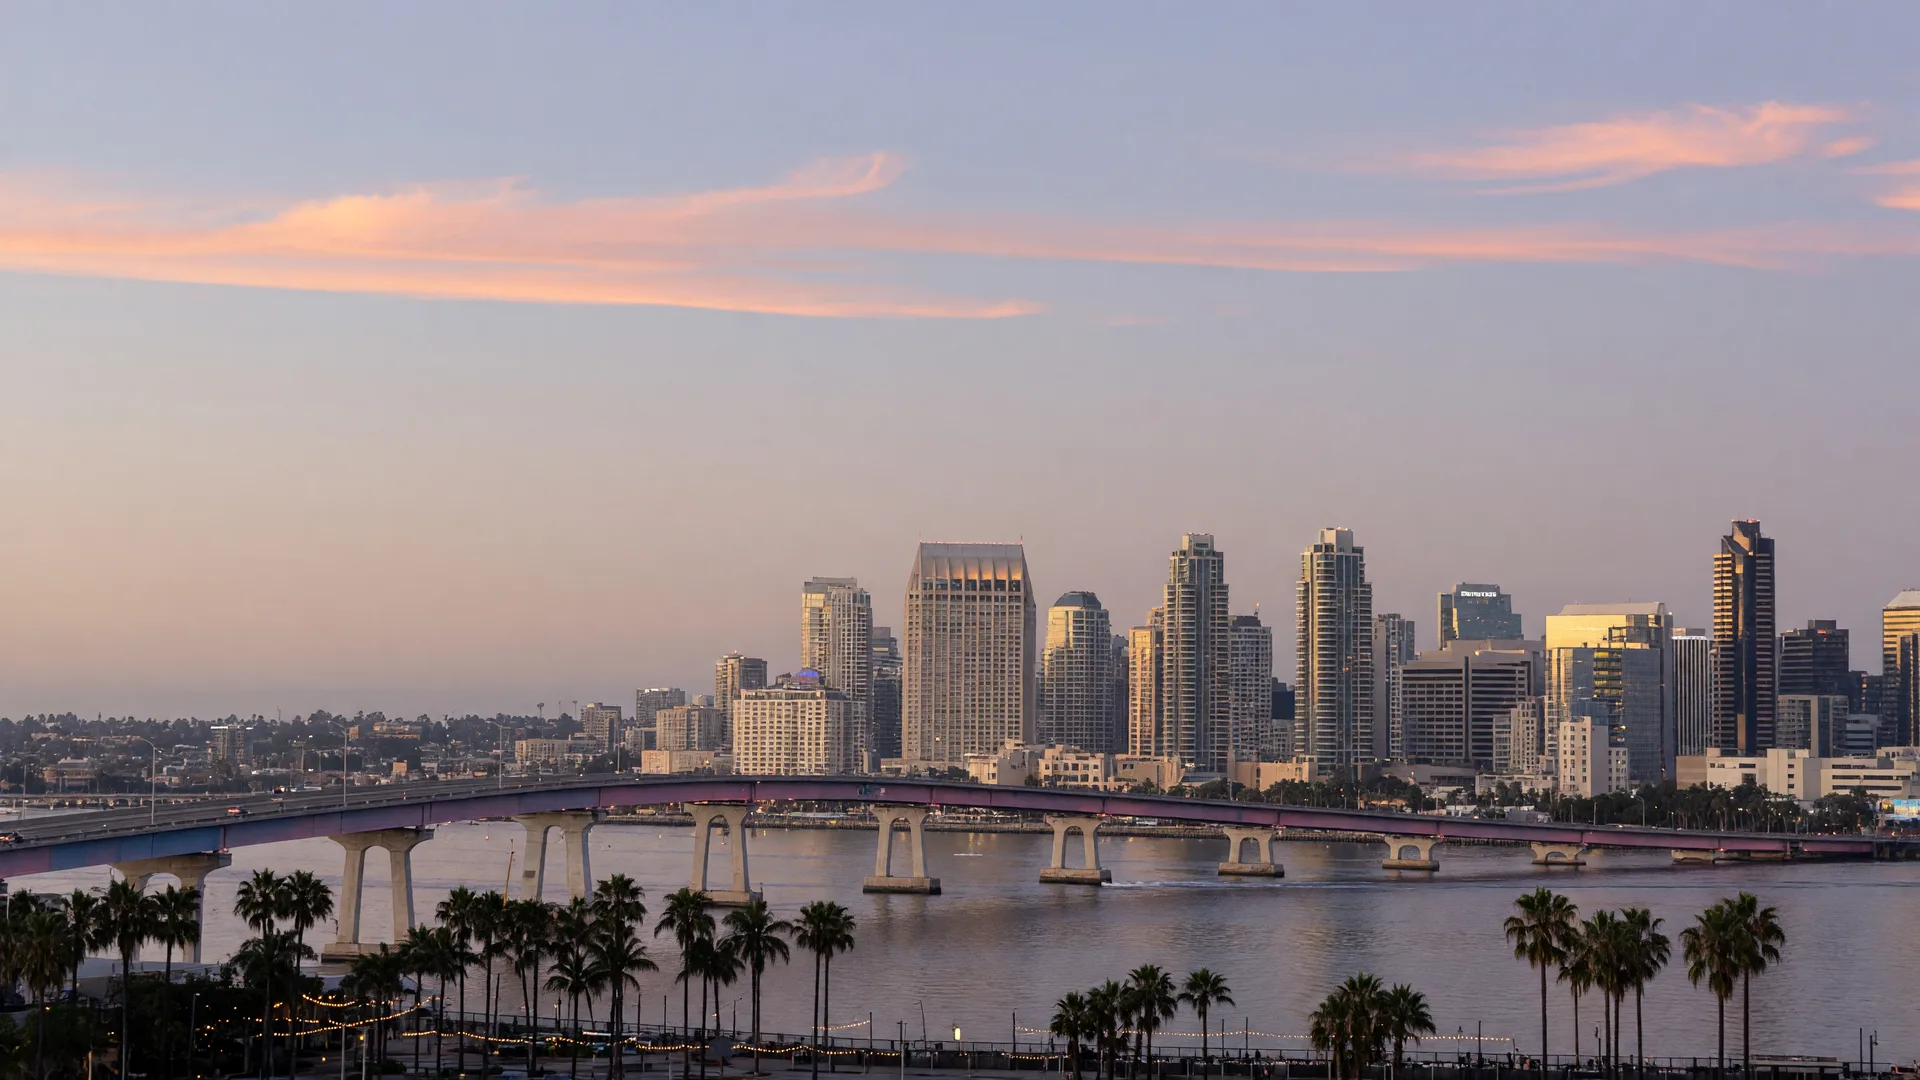
On Wednesday, September 16, the Federal Reserve raised its benchmark interest rate by a quarter point to a target range of 3.75% to 4.00%: its first hike since 2023, in a unanimous 12 to 0 vote. Mortgage rates responded by climbing to their highest levels in over a year. For anyone buying, selling, or investing in San Diego real estate right now, this decision changes the math on timing, financing, and negotiation, and I want to walk you through what it actually means for our market.
After 18+ years as an agent, an investor, and an owner in this county, I have watched San Diego absorb every rate cycle since 2008. The one thing I can tell you with confidence is that the Fed does not set your mortgage rate directly, bond markets set expectations, and buyers, sellers, and investors who understand that distinction tend to make calmer, smarter decisions. So let us separate the headlines from the numbers that matter here at home.
What the Fed Actually Did on September 16
The decision was straightforward: a 25 basis point increase bringing the federal funds rate to 3.75% to 4.00%, with Chair Kevin Warsh citing inflation that is still running hot at roughly 3.4% year over year, above the Fed's 2% target. He also signaled that at least one more hike could come before year's end, and futures markets are now pricing rates near 4.1% by December.
Mortgage rates moved in sympathy. The average 30-year fixed rate hit a one-year high of about 7.08% on September 16, up 0.30 percentage points from 6.78% a week earlier, with some trackers showing mid-September quotes near 7.4%. Freddie Mac's Primary Mortgage Market Survey had the 30-year fixed averaging 6.76% in the week ending September 10. Whatever the exact number on any given day, the direction is clear: borrowing costs are up, and they are expected to stay up through the fall.
What This Means for San Diego Buyers: Same Market, Less Buying Power
Here is the local picture. The latest published county data, from Redfin's August 2026 report, shows the median San Diego County home price at about $961,781, up 5.7% year over year, with homes selling in a median of 28 days and active inventory down 5.6% from a year earlier. More than a third of sales still closed above asking price. This is not a market in freefall. It is a supply-constrained market where higher rates quietly reduce your purchasing power.
A quarter point adds roughly $180 a month on a $900,000 mortgage, and every half point takes real money out of your budget. That is why the strategy I recommend to buyers has not changed, it has sharpened: get pre-approved this week, not next month, and lock a rate the moment you find the right home. With homes sitting a bit longer and sellers offering 1% to 3% in concessions, the buyers who move now face less competition than they did in June, and that is a real advantage. First-time buyers often find their entry through attached homes in Mission Valley, Normal Heights, North Park, or Chula Vista, where prices sit below the county median and equity builds from day one. My Buying Guide walks through pre-approval, offer strategy, and negotiation built for exactly this rate environment.
What This Means for Sellers: Prepare, Price Honestly, and Communicate
If you are thinking about selling, do not let the rate headlines talk you into waiting. Prices in San Diego are resilient, especially in the tight-supply neighborhoods buyers love, but the rules of the game have shifted. Days on market are stretching toward 29 days at the county level, and buyers are more discriminating. The first two weeks of a listing still decide its trajectory, and homes that are priced honestly, staged well, and marketed professionally are still selling close to asking while overpriced listings sit and accrue stigma.
This is where my communication commitment matters most. Poor communication and lack of updates are the number one complaint I hear from clients who came to me after a bad experience with another agent. You should never wonder where your sale stands, and you should always know exactly what the latest rate movement means for your price point. The full playbook, from pre-sale repairs and staging to concessions and negotiation, is on my Selling Guide, and my article on pre-sale home repairs that pay off in 2026 covers what is worth doing before you list.
The Military Buyer Advantage: Your Rates Are Better Than the Headlines
As a military spouse, this is the part I care most about. VA loans continue to offer some of the best pricing in the market: as of September 16, 30-year fixed VA purchase rates were around 6.375%, with some credit unions advertising prices near 5.875%, and VA buyers still get zero down, no private mortgage insurance, and a funding fee waiver for many disabled veterans. When headline rates top 7%, that advantage is enormous.
If you are PCSing this fall to Camp Pendleton, Naval Base San Diego, or MCAS Miramar, the VA appraisal and inspection process now fits comfortably inside your timeline because homes are staying on the market longer. My Military and Veterans page covers neighborhood strategy and the BAH math from someone who has made these moves herself, and with the MCAS Miramar Air Show just over a week away, it is a great season to scout the areas near the base.
What This Means for Investors: Patience Pays in a Higher-Rate Market
Investors feel rate hikes more than anyone, and September has cooled the rush to buy at any price. That is not a warning, it is an opening. Serious investors, including my own portfolio, lean into value-add properties in neighborhoods near bases, transit, and job hubs, where the gap between asking price and true after-repair value is widest. Sellers are more willing to negotiate today than they were in the spring, and that is where disciplined buyers win.
My commercial contracting background matters here: when I look at a property, I can price the renovation in hours, not weeks, and I know exactly which upgrades a San Diego rental market will reward. If you are deciding whether to hold, sell, or buy an investment property at these rates, I would love to run the numbers with you the way I run them for my own. The Investment Properties page explains how that analysis works.
Where Are You Headed Next?
Here is my honest read of September 2026. Rates are higher than they were a month ago, and they may go higher still. But San Diego prices are holding, inventory is still scarce, and the buyers and sellers who plan around the rates instead of freezing in front of them are quietly getting the best outcomes. The market is always telling you something, and right now it is telling you that preparation beats panic.
What is your biggest challenge? Where are you headed next? That is where every conversation I have starts, because the right decision for you depends on your situation, not on what the headlines say for someone else. Clear data, honest guidance, and a relationship built on trust have been the foundation of my practice for 18+ years, and they would be the foundation of yours too.
Hanna Bederson
Real Estate Agent, Investor & Military Spouse · San Diego · DRE #02096870
Wondering what the Fed's rate hike means for your specific move?
Let's Talk StrategyIn service, Hanna